China at least 5 years behind in lithography: strategist
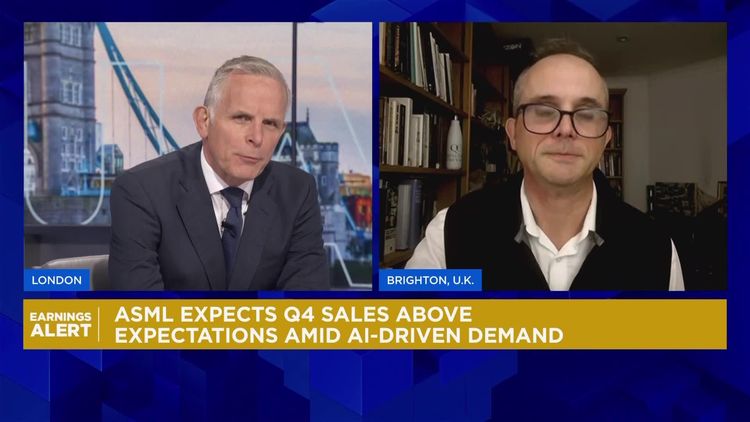
ASML Holding, the Dutch semiconductor equipment manufacturer, reported third-quarter net sales of €7.5 billion and net income of €2.1 billion, exceeding company guidance as demand for both advanced and legacy chipmaking tools remained robust. The company raised its fourth-quarter sales expectations, citing accelerating orders linked to artificial intelligence applications.
The Veldhoven-based firm, which holds a monopoly position in extreme ultraviolet lithography systems with 100% market share and controls approximately 90% of the global lithography equipment market, attributed the stronger-than-anticipated performance to higher sales of deep ultraviolet systems and installed base management services. Revenue surpassed internal projections despite narrowly missing some analyst forecasts.
Ben Barringer, Global Head of Technology Research and Investment Strategist at Quilter Cheviot, analyzed the results and emphasized the significant technological gap between ASML and Chinese competitors. His assessment that China remains at least five years behind in lithography capabilities reflects a conservative estimate of the actual disparity facing the world's second-largest economy.
Technology Gap Wider Than Commonly Perceived
Technical assessments indicate China's domestic lithography technology lags considerably further behind than the five-year minimum suggested by Barringer. Chinese manufacturers' deep ultraviolet systems demonstrate performance roughly equivalent to ASML's tools from 15 years ago, representing approximately four generations of technological advancement. Industry experts project China is unlikely to achieve commercial-scale production of advanced lithography equipment capable of manufacturing sub-10nm chips before the early-to-mid 2030s.
The technical complexity underlying this gap is substantial. ASML's extreme ultraviolet lithography technology operates by vaporizing molten tin droplets with laser pulses fired at rates of 50,000 times per second, generating extreme ultraviolet light with a wavelength of 13.5 nanometers. These systems consist of over 100,000 components, weigh 180 tons, and require a global supplier network exceeding 5,150 companies. ASML produces only about 15% of components internally, underscoring the intricate international collaboration required for production.
The most advanced High-NA EUV systems command prices between €320 million and €400 million, with the first unit delivered to Intel in December 2023. This massive capital requirement, combined with the technological and supply chain complexities, presents formidable barriers to independent development.
AI-Driven Demand Reshapes Market Outlook
ASML's optimistic fourth-quarter forecast reflects broader industry dynamics as artificial intelligence applications drive unprecedented demand for advanced semiconductors. The company raised its 2026 sales outlook to a range of €44 billion to €45 billion, up from a previous projection of €43 billion to €45 billion, specifically citing accelerating AI-related equipment orders.
CEO Christophe Fouquet indicated during the earnings announcement that customer discussions increasingly focus on periods beyond 2027, with some clients expressing interest in placing orders for delivery in 2029 and 2030. This extended order visibility suggests AI-driven demand is expected to outpace manufacturing capacity for years to come.
However, the company tempered its near-term expectations, projecting full-year 2025 total net sales between €30 billion and €35 billion. This represents the lower half of the range provided at the company's 2022 Investor Day, reflecting what management characterized as a more gradual market recovery than previously anticipated.
The divergence between robust AI-related demand and a measured overall recovery highlights the semiconductor industry's transition period, as traditional computing markets stabilize while artificial intelligence applications create new growth trajectories. For ASML, the world's sole manufacturer of EUV lithography systems essential for producing the most advanced chips, this positioning proves advantageous as customers invest heavily in next-generation manufacturing capabilities.
The company's performance and forward guidance underscore its central role in the global semiconductor supply chain, particularly as geopolitical considerations and technological advancement timelines create persistent competitive advantages that appear likely to endure well into the next decade.